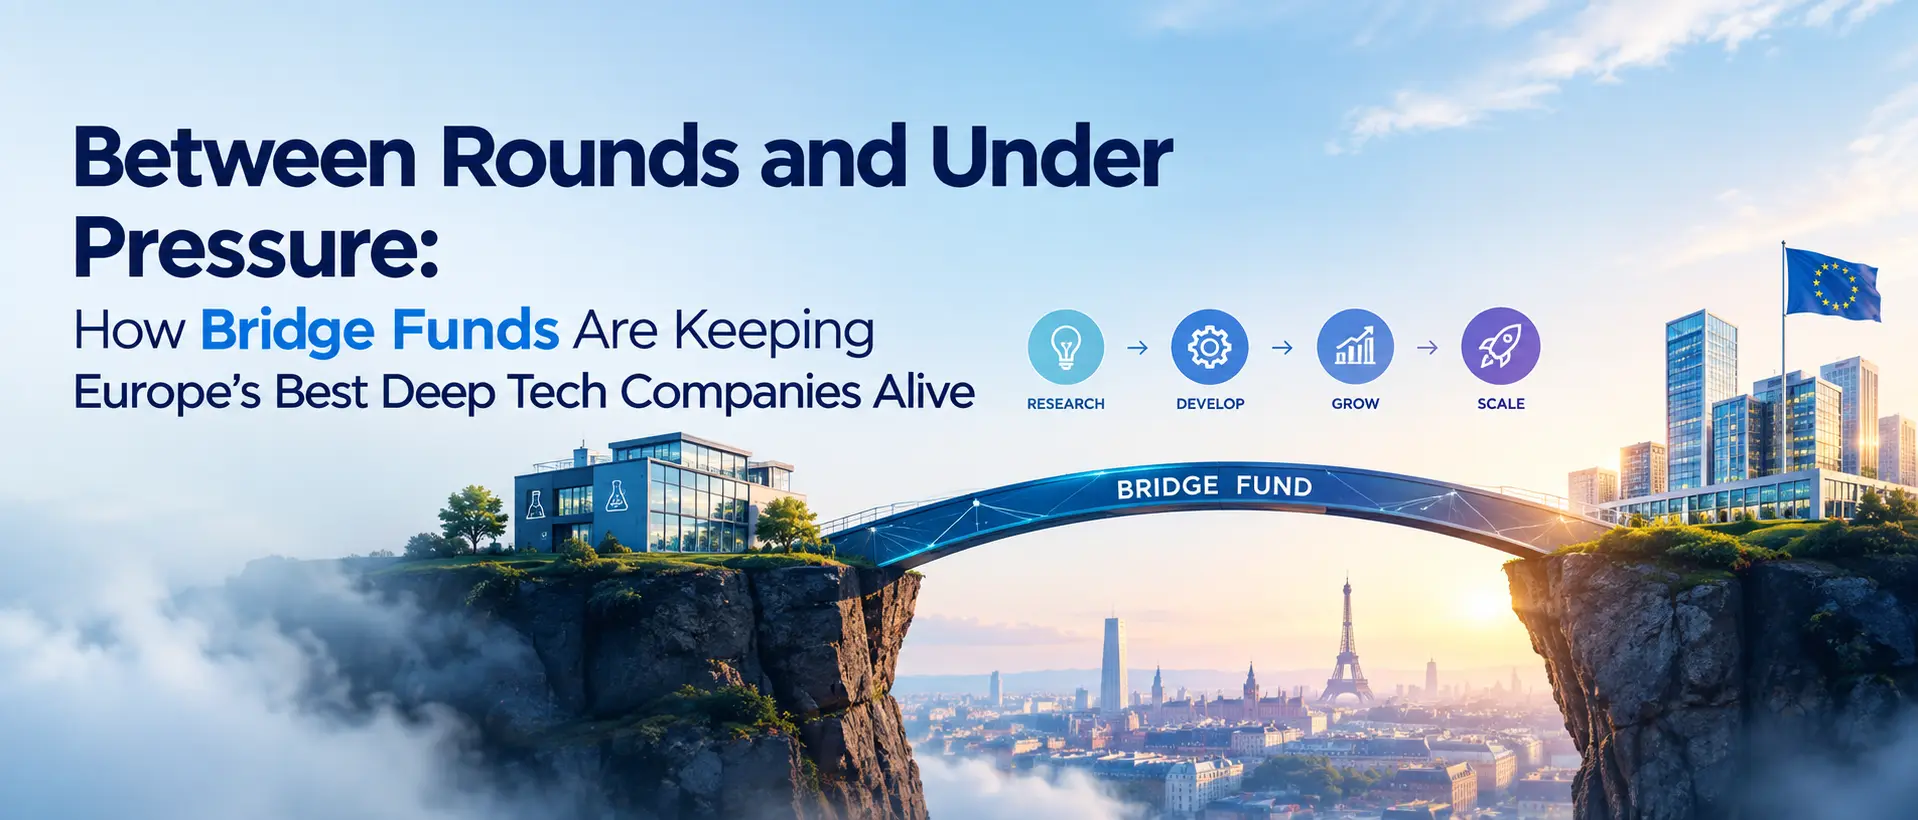
Between Rounds and Under Pressure: How Bridge Funds Are Keeping Europe’s Best Deep Tech Companies Alive
In the lifespan of most deep tech firms, there is an instant when the biggest risk is not the rivalry, the technology, or the industry. It is a calendar.
Everything is in place. The product is working. The pilot is running. Funding is already in progress. But the gap between today and the closing of amounts is greater than the cash flow in the account. At this point, the successful European deep tech companies distinguish from those that remain unsuccessful, not because their products are not exceptional but because their financial support system does not provide them with the necessary help.
Bridge financing exists exactly for that type of situation. The founders should know why this financing is important and how it works in order to be able to receive the necessary funding in the present-day environment of financing in Europe.
The Structural Problem Bridge Finance Is Solving
Europe’s deep tech ecosystem has a funding architecture problem that sits between its strongest assets. Early-stage funding has improved materially more startups are getting off the ground, more seed capital is available, and the policy environment has never been more actively supportive of science-driven company building.
However, from Series A and on, the dynamics change. Startups with reduced technical risk fail to raise the next round because they don’t have revenues at a level anticipated by institutional investors yet. The product functions, but the cash is still somewhere far away. The costs are high, the timeframes are long, and the capital requirements are surging.
This is when companies need strong funding the most but getting money is the hardest.
Seventy percent of late-stage investments in European deep tech companies come from investors outside of Europe. Companies raise much less money than they could, exit much earlier than they had planned, or take money from foreign investors instead. What differentiates lucky companies from the unsuccessful ones is that success does not rely on luck. Companies that reach their next funding round quickly have stronger positions between rounds because their investors know that bridge financing is not a secondary instrument.
France: A Case Study in the Bridge Finance Gap
No ecosystem in Europe best exemplifies the difficulties of the bridge finance dialogue better than France. Seven years after launching the Deeptech Plan, France achieved a record value of €4.1 billion in 2025—quadruple what was raised at the program’s inception in 2019—approximately half of all the French Tech fundraising. In short, France has been able to create one of Europe’s best deep tech ecosystems.
However, the early stage climate is currently less inspiring since investment is tightening and the gap in private capital is widening. French venture capital is crying for change as it found itself squeezed between mini funds and giants struggling to secure the next fund, losing outsized series A rounds to foreign players while the local talent is leaving.
This structural tension between funding records and ever-tightening early stage capital alongside growing mid-stage gap mean that the need for bridge finance has never been more relevant. Bridge financing allows firms to keep a grip on their cash flows while they wait for more serious financing and, when done correctly, it can avert cash flow troubles that would otherwise impede the companies’ growth efforts. For a French deep tech firm that has solid technology and is preparing for its credible Series B, a good bridge does not necessarily show weakness, but is rather a sign of advanced capital strategy.
France’s institutional response to this gap has been significant as well. Under the Future Investment Programs Bpifrance created French Tech Bridge program that provides bridge equity financing for a period of 6 to 24 months targeted at startups less than eight years old that are already in the process of fundraising. The adoption of this policy instrument has allowed to maintain viable companies in difficult times. However, institutional bridge programs run on their own clocks and eligibility criteria that do not always match the relentless timing of deep tech companies.
Bpifrance also launched a new Deeptech Seed Accelerator in 2026, supporting seventy-five companies across three cohorts, aiming to bridge the gap from research lab to funded startup. These initiatives are meaningful but they address the earliest end of the funding spectrum. The mid-stage bridge gap, between a validated Series A company and a growth-ready Series B, remains the most acutely underserved point in the French and broader European deep tech capital stack.
What Separates Effective Bridge Finance From Harmful Interim Capital
Not all bridge finance is created equal and when it comes to deep tech entrepreneurs, the distinction between well-designed and badly-designed bridge financing can have far-reaching implications in determining how the next institutional financing round will take place and on what terms.
Good bridge finance accomplishes three things at once. It gives enough of a runway to provide the opportunity of actually achieving significant milestones instead of just keeping afloat. It has been structured such that it does not have burdensome conversion terms that would misalign the interests of incoming Series investors. Additionally, it is provided by a fund that has the network and reputation that can help in the fundraising process.
It is important to note that bridge financing provided by a fund that does not possess sector expertise and useful network amounts to being funded without any leverage. It will ensure that the company stays afloat, but will do nothing to raise chances for closing the following round. The best bridge funds in France and Europe are increasingly being regarded by the founders as strategic partners in a particular stage of their journey and not only as lenders of last resort.
The median time between seed and Series A in Europe has stretched to twenty-two months, up from sixteen months in 2021. Between Series A and Series B, the gap is wider still for deep tech companies with hardware development cycles. This extended timeline is not a failure of the European ecosystem. It is a reflection of the genuine complexity of building science-driven companies at commercial scale. What it demands is a bridge finance infrastructure that is designed around these timelines rather than imposed against them.
Boundary Holding: Bridge Capital Built for Deep Tech’s Most Critical Window
For deep tech companies navigating the pressure between rounds particularly those building in AI, robotics, autonomous drone systems, and advanced sensor technologies the choice of bridge partner determines not just whether they survive the interval, but whether they emerge from it stronger.
Boundary Holding, an undertaking located in Luxembourg and extending its operations in Europe, is in a position where it has immense potential for growth and fulfilment of strategic goals. Through its model the business is reaching out to potential deep tech groups that have promising prospects in the near future and can therefore benefit from certain relations and knowledge the firm possesses. In particular, by providing financial and networking assistance to a company in its portfolio that reaches the stage between rounds, the company ensures that the nearest round becomes not just a reality but a successful step to the next one.