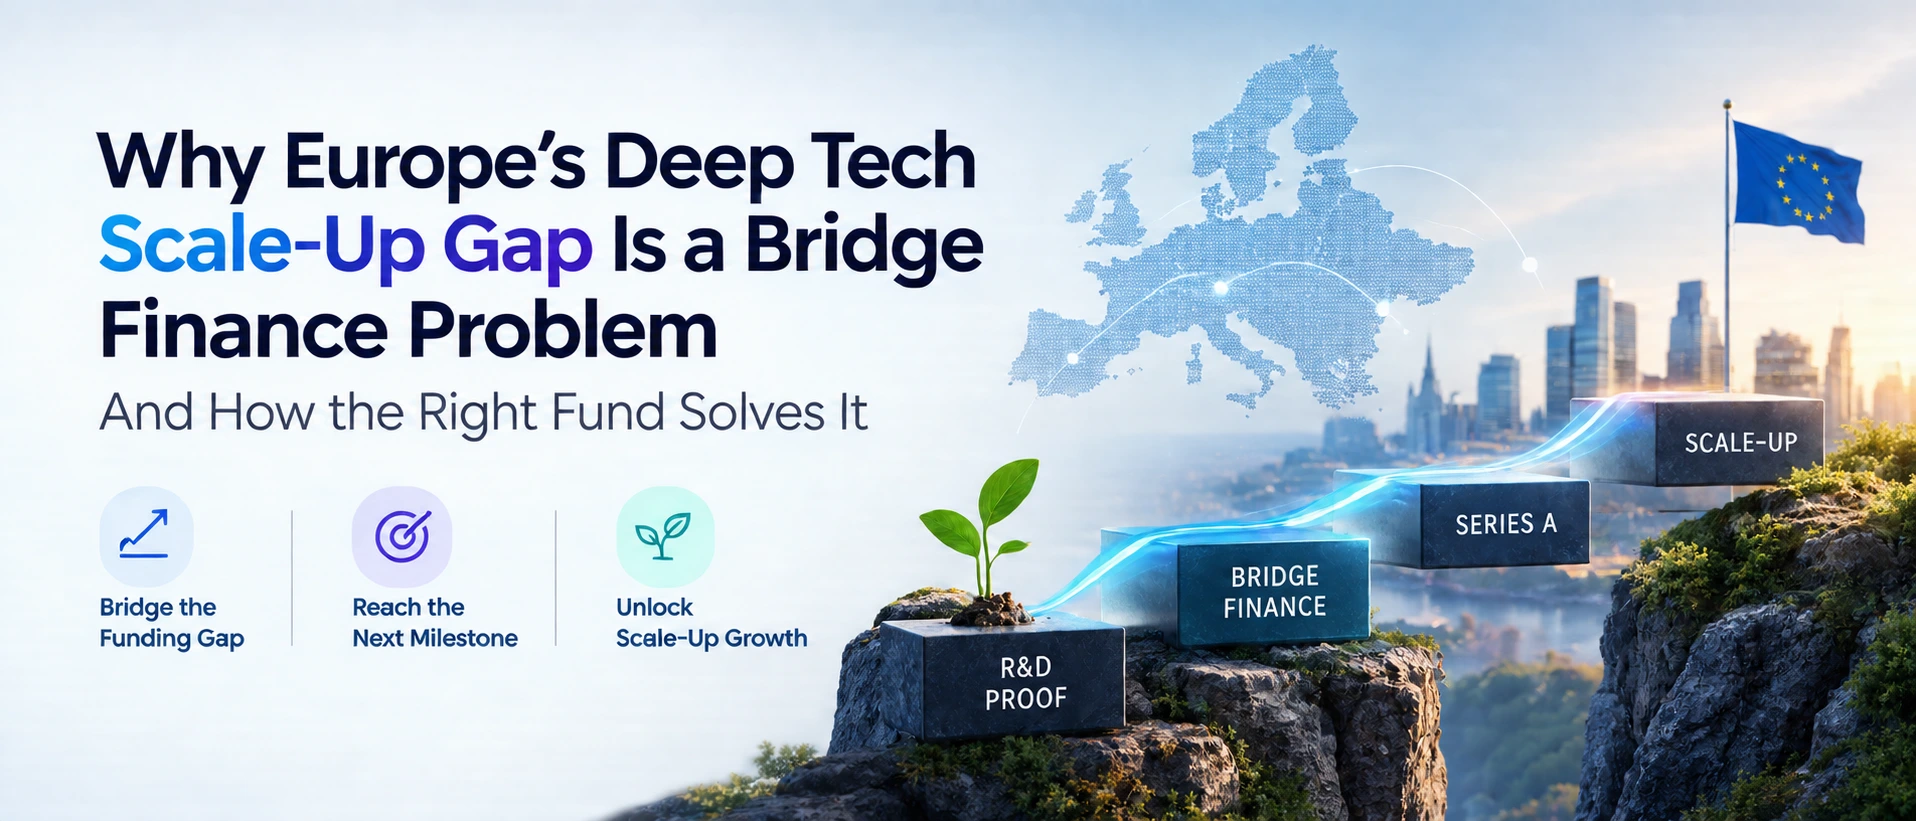
Why Europe’s Deep Tech Scale-Up Gap Is a Bridge Finance Problem And How the Right Fund Solves It
Every European deep tech owner who has successfully raised money and set up something that works is left bewildered and confused by the question: what comes next?
The response is often silence for long periods of time. The seed system in Europe has developed adequately. Europe shows outstanding research basis as it has almost a third of the leading deep tech universities in the world and produces more scholars and engineers than any other place in the world.
But at the very moment when it is required for deep tech companies to grow from accepted technology to the next level, the European finance system fails them.
It has its name – the scale-up gap. The understanding of the scale-up gap as a reality of life for entrepreneurs and investors is the first step toward solving the problem.
The Gap Is Not Where Most People Think It Is
The standard tale purports that the caution, scarcity, and excessive risk aversion of European investors adversely compare, thus rendering them unfit for venture capital in it; this narrative is simplified and misleading in an important way.
Underpinning is a structural rather than a cultural issue; Europe produces almost half the deep tech startups across the world yet raises but a fraction of global financing volume in return; Series A to Series B conversion rates in Europe are a fraction of rates seen in North America. More than 90 percent of the startups fail because there is no funding while they have proven their technology but still have to achieve commercial traction that would attract a large institutional growth round-plenty of this funding does not arrive at the right moment.
This is not merely the onset of the problem-every early stage venture capital cannot find escape in the existence of funds meant for European deep tech but appears not evenly distributed as some early-stage numbers tend to drop as their growth has come in. In that window which, for capital-intensive hardware and science-based businesses, can last years the company is simultaneously its most vulnerable and its most valuable.
This is precisely where bridge finance enters, and where its absence is most acutely felt.
What Bridge Finance Actually Does
Bridge financing is often misunderstood, having an association with bad practice in the startup sphere but this association especially hurts deep tech companies.
When one is creating autonomous systems or the burden of responsibility lies in developing advanced sensors, quantum hardware, or AI-driven industrial infrastructures the timeline is not a signal of inefficiency but rather a crucial characteristic of technology. One should not think of the distance from lab proof-of-concept to commercial use as a negative but rather see it as a competitive advantage in its own right. When placed properly by a fund that understands the circumstances in which the deep tech company operates bridge financing is not a second-best option but rather a powerful tool.
The function of a bridge financing provider is to extend the runway for the deep tech company and enable it to reach the next significant milestone without giving away parts of its business to those who do not understand the business model or moving to another country to access financing.
Europe has recognised this urgency institutionally. The Scaleup Europe Fund, established to bridge the late-stage investment gap for European deep tech scale-ups, was designed in partnership with private investors to expand internationally while remaining rooted in Europe. The European Innovation Council’s STEP Scale Up mechanism offers capital between the grant stage and large private rounds. These are meaningful structural responses but they operate on timelines that do not always align with the competitive windows founders face. Private bridge capital, from the right specialist fund, moves faster and brings more than money.
Why the Fund Behind the Bridge Matters as Much as the Capital
Not all bridge capital yields the same value. A bridge investment from a generalist fund that does not possess any sector knowledge, any industry connections, or any understanding of deep tech innovation cycles provides a solution to a cash flow issue but raises a governance issue. The associates of the fund will not know what metrics their company should be judged against. They will not understand what collaborations with business partners will help them achieve commercial approval faster. They will have no knowledge of the licensing processes that will dictate the time of the mass rollout of the technology.
That is why the crucial question that the founder of a deep tech startup should ask about bridge financing is never just how much money and on what conditions. More important questions include whether this fund has enough familiarity with the founder’s project to help the person reach the next goal, whether they have connections that the founder lacks, and whether they are adaptable enough in terms of their fund’s duration, their reserve for unexpected situations, and their limited partners’ endurance to provide funds needed after the usual timeframe in venture financing.
The best deep tech investors in Europe have built their models around precisely these questions. They bring technical depth at the investment decision level, not outsourced to advisors. They bring industrial networks that connect portfolio companies to pilot customers, corporate partners, and co-investors who understand hardware and science-based businesses. And they bring structural patience fund architectures with longer lives and higher reserve ratios than conventional venture vehicles, because they understand that the most consequential deployment often happens in the follow-on, not the first cheque.
The Compounding Cost of Getting This Wrong
Not all bridge capital yields the same value. A bridge investment from a generalist fund that does not possess any sector knowledge, any industry connections, or any understanding of deep tech innovation cycles provides a solution to a cash flow issue but raises a governance issue. The associates of the fund will not know what metrics their company should be judged against. They will not understand what collaborations with business partners will help them achieve commercial approval faster. They will have no knowledge of the licensing processes that will dictate the time of the mass rollout of the technology.
That is why the crucial question that the founder of a deep tech startup should ask about bridge financing is never just how much money and on what conditions. More important questions include whether this fund has enough familiarity with the founder’s project to help the person reach the next goal, whether they have connections that the founder lacks, and whether they are adaptable enough in terms of their fund’s duration, their reserve for unexpected situations, and their limited partners’ endurance to provide funds needed after the usual timeframe in venture financing.
Boundary Holding: Bridge Finance Designed for the Scale-Up Moment
Boundary Holding has developed its business model to operate the junction where deep technology investment meets bridge financing, taking into consideration the fact that during the scale-up stage of Europes deep-tech companies there exists a unique structural gap.
The headquarters of Boundary Holding are situated in one of the most efficient European domicile firms for investing in cross-border funds, Luxembourg. Operations of the company are aimed at investing in such sectors as artificial intelligence, robotics, autonomous drone technology and advanced sensor technologies.
The best deep tech investors in Europe understand that bridge finance is not a transaction. It is a relationship one that determines whether a company navigates its most vulnerable phase with strategic advantage or with its energy drained by capital uncertainty. Boundary Holding’s deep alignment with European Innovation Council priorities and the Strategic Technologies for Europe Platform gives portfolio companies access to the institutional networks, government innovation programmes, and co-investment pipelines that transform bridge capital from a temporary solution into a genuine commercial accelerant.
Europe’s deep tech scale-up gap is real. Bridge finance, from the right fund, is how it gets closed one high-conviction investment at a time.